

 Debt
 10 steps
Quick answer: what to do now
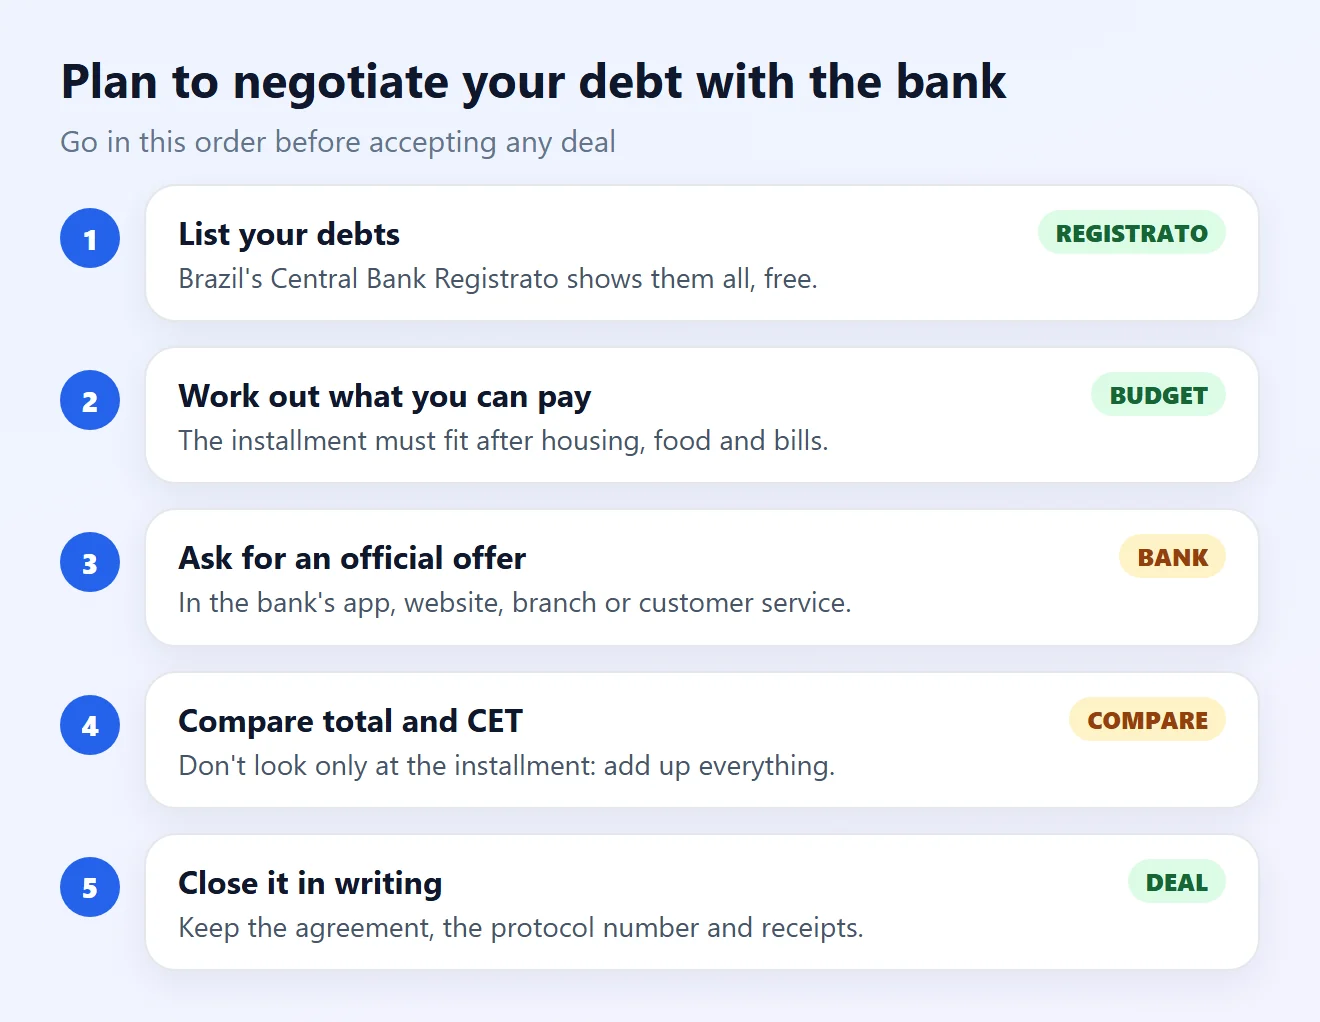
- See all your bank debts in the Central Bank's Registrato. It's free.
- Work out the highest installment that fits your budget after housing, food and basic bills.
- Ask for an offer only through the bank's official channels: app, website, branch or customer service. Write down the protocol number.
- Compare the total paid and the CET (total effective cost) of each offer, not just the installment.
- Close the deal in writing and only pay a boleto or Pix that shows the bank as the payee.
This guide follows Brazilian rules. The federal debt renegotiation program for families ended on 31/08/2026. Today you negotiate directly with each bank, and the government warns it doesn't use websites, links or SMS to renegotiate debts.
Which case is yours?
How to negotiate debt with a bank: 10 steps
1List all your debts in Registrato
Before you call the bank, know exactly what you owe. Registrato, from Brazil's Central Bank, shows your debts and loans at every bank for free.
- Sign in through Meu BC with a gov.br silver or gold account and two-step verification turned on.
- Open the loans and financing report and note, for each debt: bank, type (credit card, overdraft, loan), amount and whether it's overdue.
- Mark the debts with the highest interest, such as revolving credit card balances and overdrafts. They're usually the first to negotiate.
2Work out how much you can pay each month
- Add up your monthly take-home income.
- Subtract essential costs: housing, food, power, water, transport, health.
- What's left is the installment ceiling for all debts together. Take that number to the negotiation.
Don't accept an installment that only fits if you skip another bill. A deal that falls behind is often canceled, and the debt comes back with interest.
3Negotiate only through the bank's official channels
Brazil's Ministry of Finance stresses that renegotiation happens directly with the banks, and the government doesn't use websites, links or SMS for it.
- Use the bank's app or website (typed in yourself), a branch or the customer service number on the back of your card or in your contract.
- Be suspicious of messages with a big discount and a short deadline, shortened links, or requests for passwords, tokens or codes.
- Write down the protocol number of each contact, with the date and the agent's name.
If the offer came by message, don't click. Open the bank's app yourself and check whether the same offer shows up there.
4Ask for a discount and every option
Tell the bank how much you can pay and ask for the available options. Always ask:
- What's the discount for paying in full? Older, overdue debts usually get the biggest discounts.
- What's the discount with a down payment + installments, over different terms (12, 24, 36 months)?
- Can you combine several debts at the same bank into one deal with lower interest?
- When is the first due date? Ask for a date right after payday.
If the first offer doesn't fit, say what does and ask for a new one. You don't have to accept on the spot.
5Compare the total paid and the CET, not just the installment
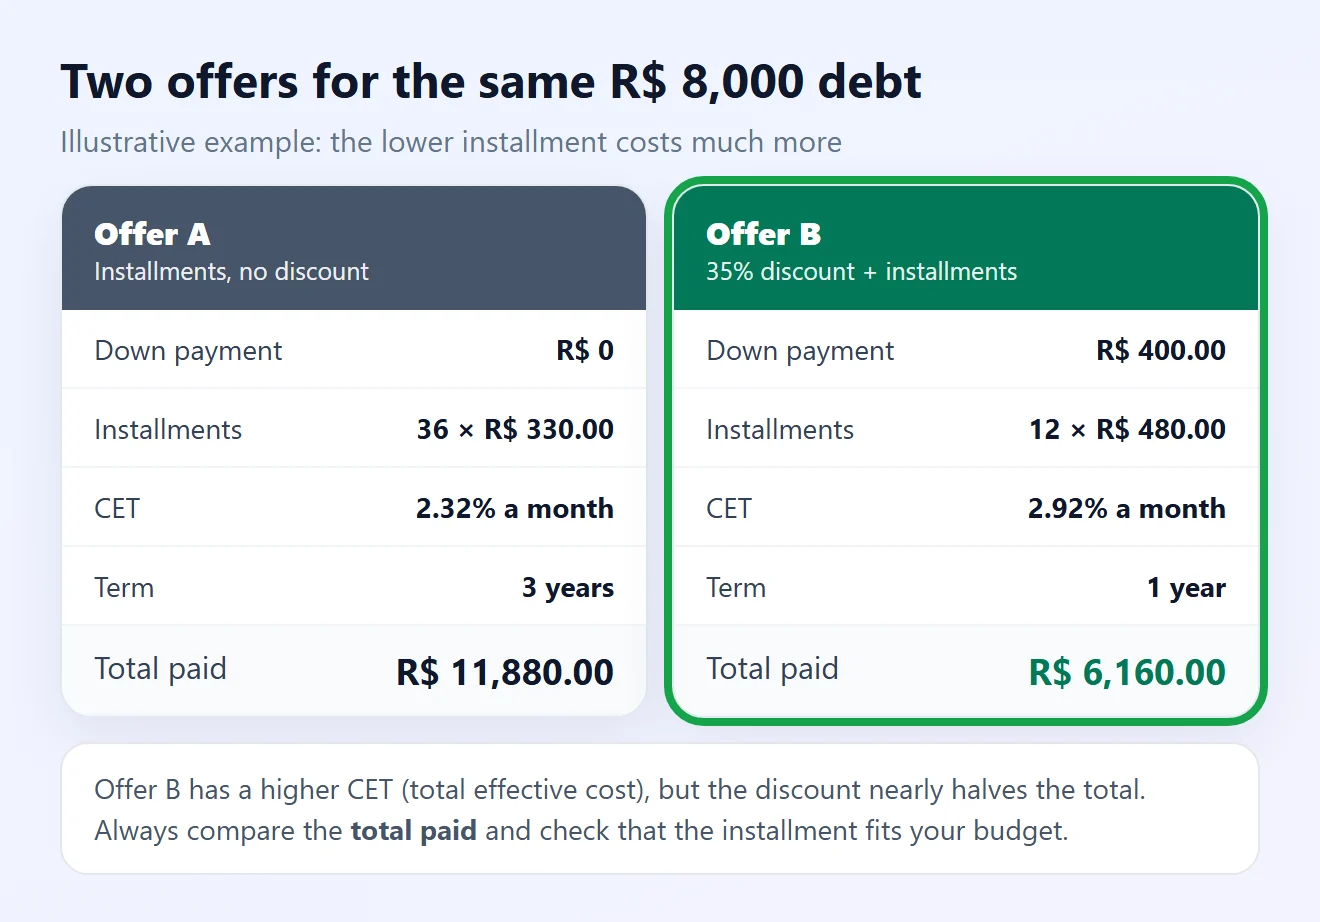
- Multiply the installment by the number of installments and add the down payment: that's the total paid.
- Ask for the CET (Custo Efetivo Total), which includes interest, fees, insurance and taxes. The bank must give it to you before you sign.
- A long term makes the installment smaller, but almost always means you pay much more in total.
- To see if the interest is high, compare it with the average for the same product on the Central Bank's Interest Rates page.
Not sure whether to pay in installments or in full? See whether to pay debt in full or in installments.
6Close the deal in writing
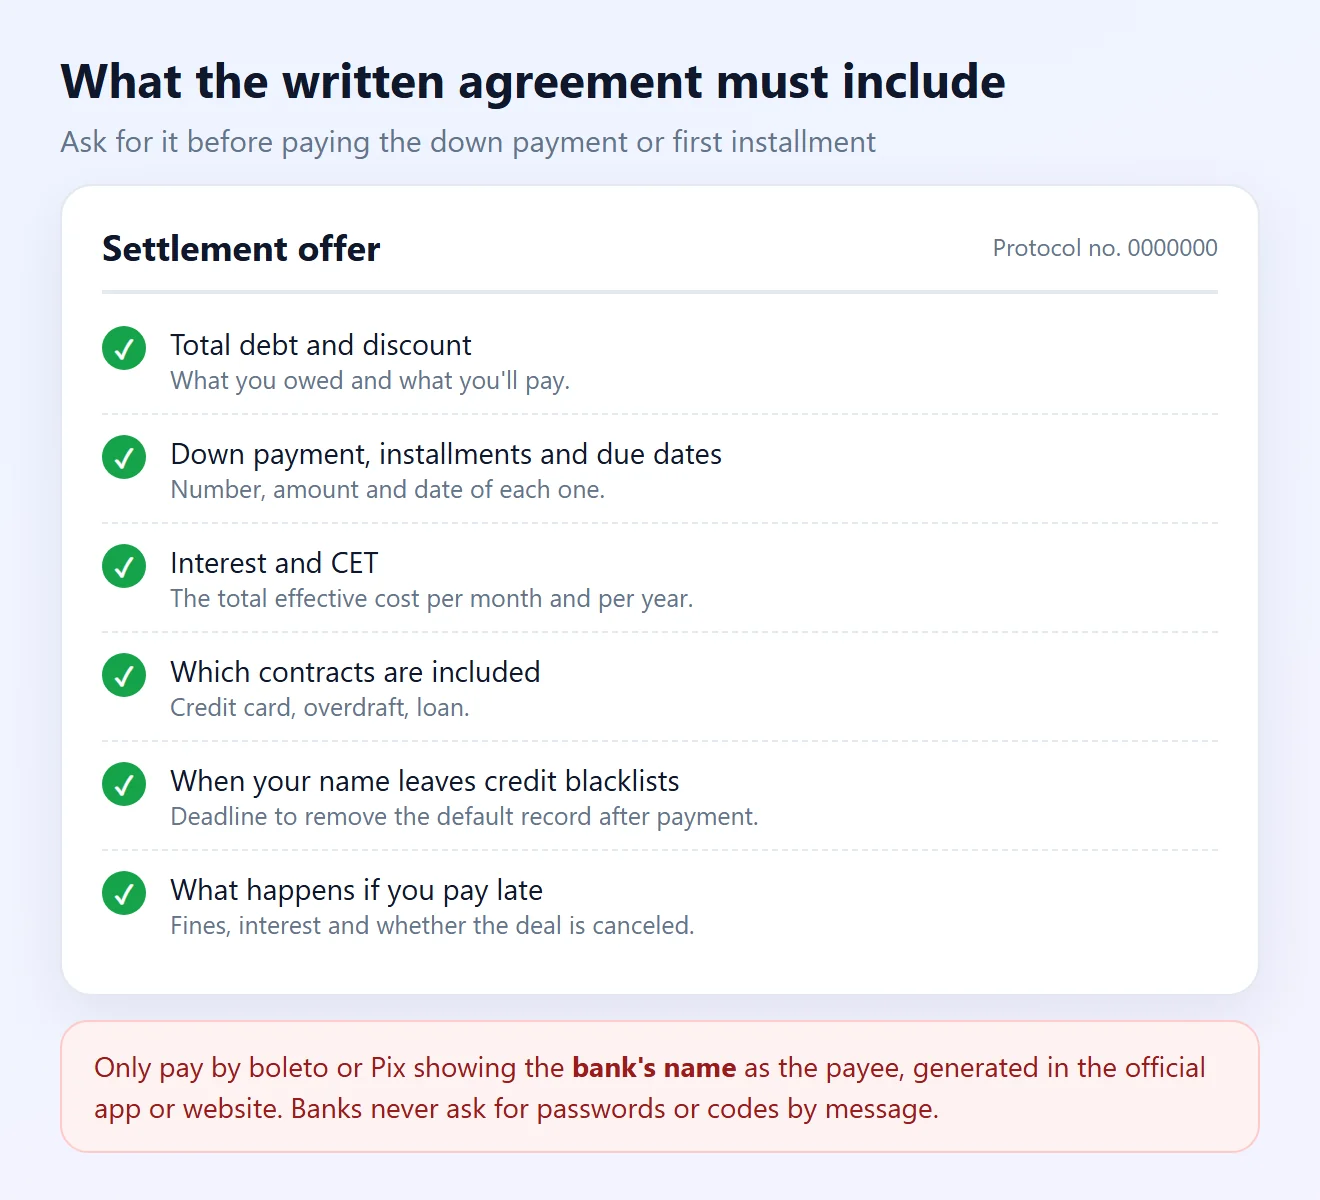
Before paying the down payment or first installment, ask for the offer in writing (in the app, by email or as a document from the branch) and check:
- The debt amount, the discount and the final amount.
- Down payment, number and amount of installments and due dates.
- Interest and CET per month and per year.
- Which contracts are included.
- When the bank will ask to remove your name from credit blacklists.
- What happens if you pay late: fines, interest and whether the deal is canceled.
Save the document, the protocol numbers and every payment receipt.
7Pay only by official boleto or Pix
- Generate the boleto or Pix inside the bank's official app or website.
- Before confirming, check that the payee is the bank itself or the collection company named in the agreement, with the same amount.
- Never pay into a personal account or anyone charging an upfront “fee” to unlock a discount.
Fell for a scam? See what to do after a Pix scam.
8Pay installments early or move the debt to another bank
If your loan is up to date but the interest is heavy, the rules give you two ways out:
- Early repayment: Brazil's Consumer Protection Code (art. 52, § 2) guarantees a proportional cut in interest when you pay installments early or settle everything. CMN Resolution 3,516 bans fees for early settlement.
- Credit portability: another bank can take over the debt at lower interest. You ask at the new bank, and your current bank can't block the transfer. The rule is CMN Resolution 5,057/2022.
Use another bank's offer as leverage: your current bank often lowers the rate to keep you. See also how to refinance a debt.
9Check that your name leaves credit blacklists
- After paying, check the credit bureaus (Serasa, SPC, Boa Vista) and see whether the record was removed by the deadline in the agreement.
- Under Brazil's Superior Court of Justice (STJ Precedent 548), the creditor must request removal within 5 business days after the debt is fully paid.
- Under the Consumer Protection Code (art. 43, § 1), negative information can't stay in credit records for more than 5 years.
10The bank didn't negotiate? Use your rights
- File a complaint with the bank's customer service (SAC), then its Ombudsman (Ouvidoria), citing the earlier protocol numbers.
- If that fails, complain on consumidor.gov.br or to the Central Bank.
- If your debts don't fit your income even after cutting costs, you may be over-indebted. The Consumer Protection Code (arts. 104-A and 104-C) lets you ask Procon or a court for a conciliation with all creditors at once, with a payment plan of up to 5 years.
- That plan must protect the existential minimum, currently set at R$ 600.00 by Decree 11,150/2022.
Learn how it works in Brazil's over-indebtedness law. The Public Defender's Office and Procon help for free.
Situation and what to do
| Situation | Best path | Step |
|---|---|---|
| Loan up to date, high interest | Pay early or use portability | 8 |
| Overdue debt and money to pay it off | Ask for a lump-sum discount | 4 |
| Overdue debt and no savings | Small down payment + affordable installments | 2 and 5 |
| Offer received by SMS or WhatsApp | Check in the official app before paying | 3 |
| Bank doesn't reply | Ombudsman, consumidor.gov.br, Central Bank | 10 |
| Income can't cover the debts | Conciliation at Procon (over-indebtedness) | 10 |
Frequently asked questions
How do I negotiate debt with a bank?
List your debts in Registrato, work out what you can pay each month, ask for an offer through the bank's official channels, compare total paid and CET, and close the deal in writing before paying.
Does the bank have to give me a discount?
No law forces a bank to give a discount in a negotiation. But it must cut interest proportionally if you pay installments early or settle the contract (Consumer Protection Code, art. 52, § 2).
Is the government debt renegotiation program still open?
The 2026 debt renegotiation program for families ended on 31/08/2026, according to Brazil's Ministry of Finance. Today you negotiate directly with each bank.
I got an SMS offering a debt discount. Is it a scam?
It may be. Don't click the link. Open the bank's app or type its website address yourself and check whether the offer is there. The government says it doesn't use websites, links or SMS to renegotiate debts.
Is it better to pay the deal in full or in installments?
Paying in full usually gets the biggest discount. If you choose installments, compare the total paid and the CET of each option and pick an installment that fits without missing other bills.
When does my name leave Serasa after a deal?
The deadline should be in the agreement. Under STJ Precedent 548, once the debt is fully paid the creditor must request removal within 5 business days.
Can the bank charge a fee if I pay off early?
No. CMN Resolution 3,516 bans early settlement fees on consumer credit contracts, and the Consumer Protection Code guarantees a proportional cut in interest.
Can I move my debt to another bank?
Yes, through credit portability. Ask at the bank that will take over the debt. Your current bank can't block the transfer, but it can make a counteroffer.
Does a debt disappear from credit records after 5 years?
The negative record can't stay in credit databases for more than 5 years (Consumer Protection Code, art. 43, § 1). The bank may still try to collect the debt by other means, within legal time limits.
What if my debts are bigger than my income?
Go to Procon or the Public Defender's Office and ask for an over-indebtedness repayment plan. It brings all creditors together, lasts up to 5 years and protects the R$ 600 existential minimum.
Related content
More practical solutions in Debt.

Compound Interest on Debt: How to Understand and Prevent Balance Growth
Entenda how to the compound interest aumentam the amount of a debt to the longo of the time, how to identify the encargos cobrados and quais atitudes helpm the reducesir the impact financial.
 15 minutes

How to Get Out of Debt: A Complete Guide to Reorganizing Your Finances
Learn how to sair of the debts with estratégias práticas of organization financial, negotiation of débitos, control of expenses and planning for recuperar your estabilidade financial.
30 minutes

Negative Credit Record in Brazil: How to Check and Resolve Outstanding Debts
Learn how to check for a negative credit record in Brazil, identify outstanding debts, negotiate with creditors, and track the regularization of your CPF safely.
15 minutes
Sources
- Brazil's Ministry of Finance: Debt renegotiation (in Portuguese)
- Planalto: Consumer Protection Code, Law 8,078/1990 (in Portuguese)
- Planalto: Decree 11,150/2022 on the existential minimum (in Portuguese)
- Central Bank of Brazil: CMN Resolution 3,516/2007 on early settlement (in Portuguese)
- Central Bank of Brazil: CMN Resolution 5,057/2022 on credit portability (in Portuguese)
- Central Bank of Brazil: Using Credit leaflet (in Portuguese)
- Central Bank of Brazil: Registrato (in Portuguese)
- Central Bank of Brazil: Interest rates by product and bank (in Portuguese)
- Consumidor.gov.br: complaints against companies and banks (in Portuguese)
The screens and comparison in this guide are illustrations made by Fixfy, with example amounts. This content is for information only and doesn't replace a review of your contract.