

 Financial budget
 10 steps
Quick answer: how to organize your monthly budget
- Write down your month's net income, adding up every source.
- List fixed bills and installments, variable costs (3-month average) and yearly bills divided by 12.
- Do the math: income minus expenses. Short? Cut waste and extras. Surplus? Save first, on payday.
- Use a table with planned and actual amounts for each line.
- Review every month, always on the same day, and adjust what went over.
What's your case?
How to organize your monthly budget: 10 steps
1Write down the month's net income
- Add up everything that comes in: net salary, side jobs, rent received, alimony, benefits.
- Use the amount that lands in your account, after deductions.
- Variable income? Use the average of recent months or your weakest month.
2List fixed bills and installments
- Fixed bills come every month at a similar amount: rent or mortgage, condo fees, power, water, gas, internet, phone, school, health plan.
- Include every installment and loan. Brazil's Central Bank warns: don't trust mental math, it tends to fail.
- Write down each due date to avoid fines.
3Estimate variable costs
- Variable costs change every month: groceries, transport, pharmacy, leisure, delivery.
- To estimate, use the average of the last 3 months from your statement and card bill.
- Set a cap for each. This is where most possible cuts are.
4Divide yearly bills by 12
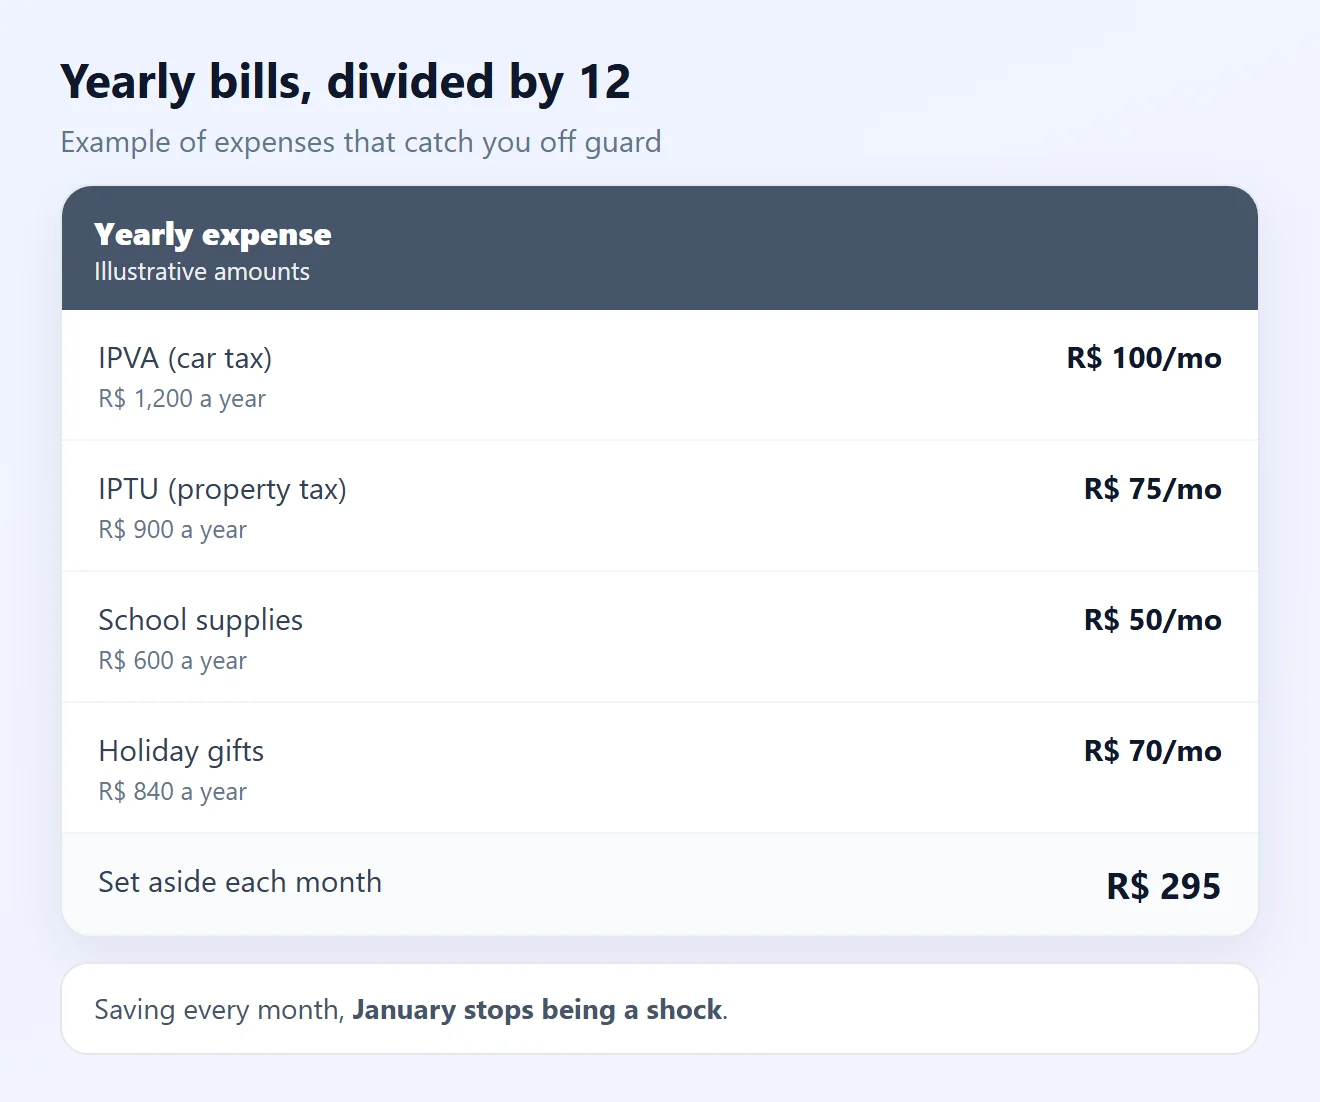
- List what's due once a year: IPVA (car tax), IPTU (property tax), vehicle licensing, school enrollment and supplies, insurance, annual fees, holiday gifts.
- Divide the total by 12 and set that amount aside every month in a separate account.
- That way, the start of the year stops being a shock and you can take discounts for paying upfront.
5Do the math: income minus expenses
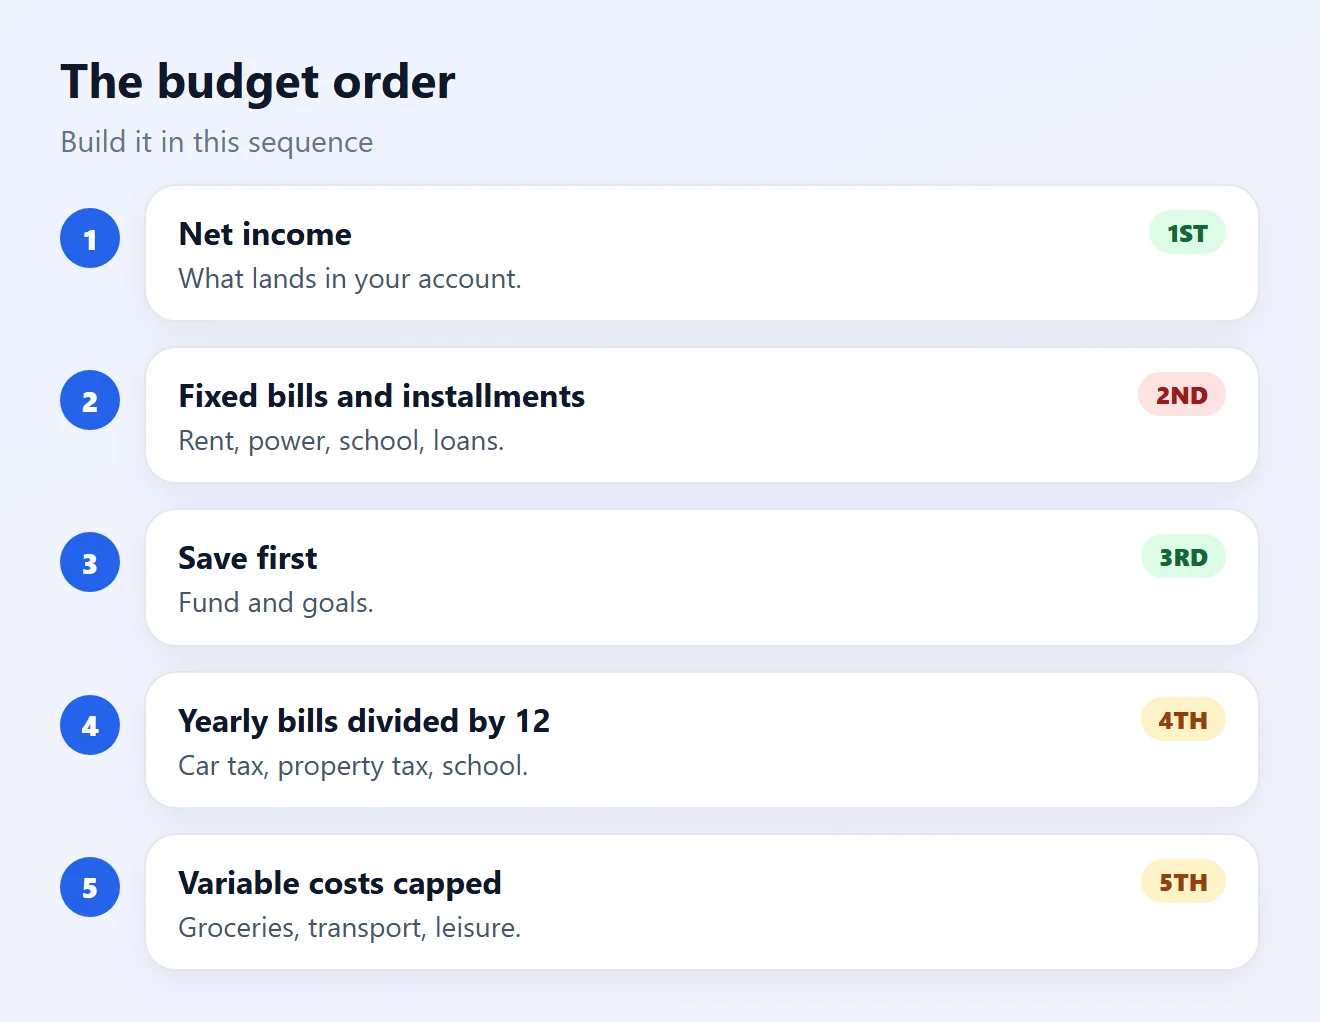
- Subtract fixed bills, yearly bills divided by 12 and variable costs from your income.
- Answer the questions Brazil's Central Bank suggests: are we spending more than we earn? Where is the money going? What can we adjust without losing quality of life?
- Example: R$ 4,000 income, R$ 2,300 fixed bills and installments, R$ 295 yearly bills, R$ 400 to save and a R$ 1,005 cap for variable costs.
6Short of money? Adjust before using credit
- Cut waste first (fines, interest, unused services), then reduce extras.
- Have expensive debts? List them all with amount, installments and interest rate and try to renegotiate.
- Avoid covering the gap with overdraft or credit card revolving credit: the problem grows next month.
- Think about ways to increase your income too.
See how to cut unnecessary expenses and how to get out of debt.
7Surplus? Save first, not at month's end
- Treat savings as a fixed bill in your budget and transfer it on payday.
- Brazil's Central Bank suggests scheduling a monthly automatic transfer to savings or a fund.
- Priority: emergency fund first, then your goals.
8Build a table with planned and actual amounts
- Make a row for each expense and two columns: planned (what you budgeted) and actual (what you really spent).
- At month's end, the difference shows where the budget went over and where money was left.
- It can be a notebook, a spreadsheet or your banking app. What matters is using it every month.
9Live with someone? Budget together
- As Brazil's Central Bank notes, a family budget is a collective project: set goals and priorities together.
- A fair way to split is in proportion to income: whoever earns more pays a larger share of household expenses.
- Agree on how much each person can spend freely, without explanations.
10Review every month, always on the same day
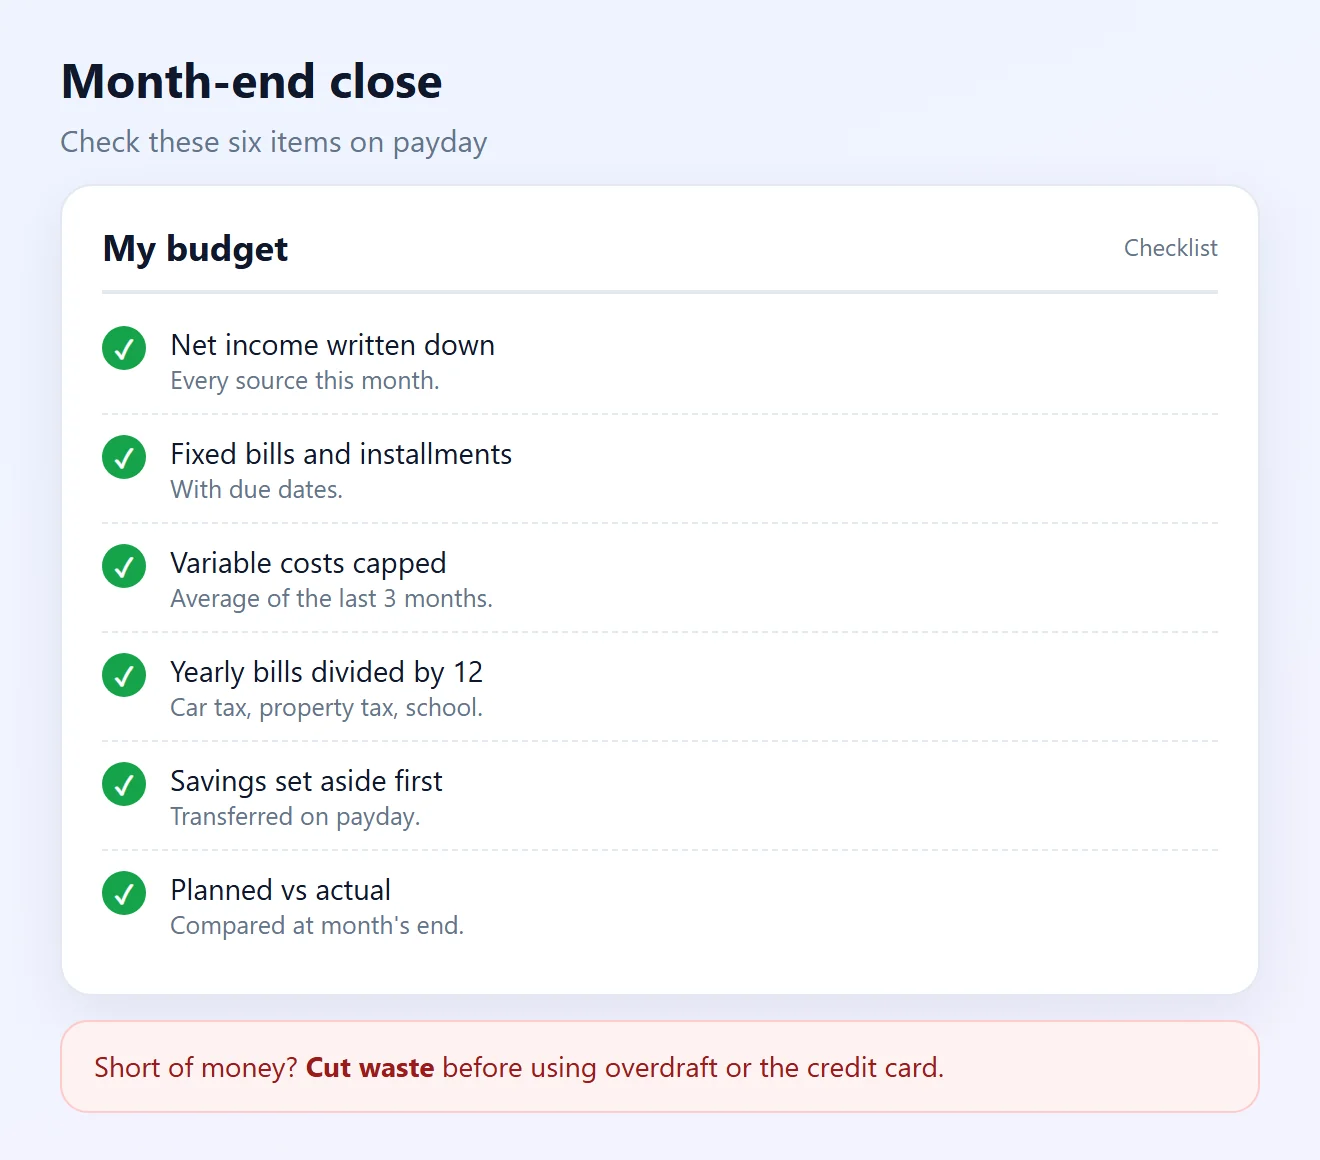
- Choose a fixed day, ideally right after payday, to close the previous month and plan the next.
- Adjust the caps based on actual spending: a good budget reflects real life.
- Income changed or a new bill appeared? Redo the math the same day.
Situation and what to do
| Situation | Likely cause | What to do |
|---|---|---|
| The month doesn't balance | Spending above income | Cut waste and extras (step 6) |
| January is always tight | Yearly bills without savings | Divide by 12 and save (step 4) |
| Surplus, but the money vanishes | Saving only at month's end | Transfer on payday (step 7) |
| Budget doesn't match reality | Variable costs guessed | Use a 3-month average (step 3) |
| Arguments about money at home | No agreement | Joint, proportional budget (step 9) |
| I start and give up | No review | Fixed review day (step 10) |
Frequently asked questions
How do I start a monthly budget?
Write down your net income, list fixed bills and installments, estimate variable costs from a 3-month average and add yearly bills divided by 12.
What's the difference between fixed and variable costs?
Fixed costs come every month at a similar amount, like rent and internet. Variable costs change month to month, like groceries, transport and leisure.
How do I include yearly taxes in the budget?
Divide the yearly amount by 12 and set that part aside every month in a separate account. When the bill arrives, the money is already there.
What if the budget doesn't balance?
Cut waste, reduce extras, renegotiate expensive debts and look for ways to increase income. Avoid covering the gap with overdraft or revolving credit.
How much should I save each month?
There's no right amount. Start with what fits and save it on payday, ideally with an automatic transfer.
Is there a percentage rule for budgets?
There are popular rules that split income into percentages, but no official rule. What matters most is that spending fits your income and something is left to save.
What are planned and actual amounts?
Planned is what you budgeted; actual is what you really spent. Comparing them shows where the budget went over.
How do I share a budget with my partner?
Budget together and consider splitting household expenses in proportion to each person's income.
How often should I review my budget?
Every month, on a fixed day, ideally right after payday. Also review it when your income changes.
Do I need an app to budget?
No. A notebook or spreadsheet works well. Your banking app helps sort spending by category.
Related content
More practical solutions in Financial budget.
How to Cancel Forgotten Subscriptions and Save Money
Find recurring subscriptions that may be consuming your budget and learn how to identify automatic charges and cancel services you no longer use.
 10 minutes
Credit Score: How It Works and What Influences Your Score
Understand what a credit score is, which factors may influence it, and how to maintain a more organized financial history.
10 minutes
How to Cut Unnecessary Expenses Without Giving Up Everything
Learn how to identify low-value spending, reduce waste, and save money without unnecessarily sacrificing your quality of life or essential needs.
30 minutes
Sources consulted
- Central Bank of Brazil: Organizing family life, family budget (in Portuguese)
- Central Bank of Brazil: Achieving dreams, budget and paying yourself first (in Portuguese)
- Central Bank of Brazil: Starting adult life, knowing your expenses (in Portuguese)
- Central Bank of Brazil: Getting out of a financial squeeze, mapping debts and cutting expenses (in Portuguese)
The images on this page are illustrations created by Fixfy. Amounts are examples.