

 Debt
 10 steps
Quick answer: what to do now
- List every overdue installment: creditor, installment number, days late and whether an asset is pledged (house, car).
- Pay first the ones that could cost you an asset (home and car financing) and your essential bills.
- Contact the creditor soon, through official channels: each month late adds contract interest and late interest.
- Ask for the updated amount in writing. Banks may only charge contract interest, a late fee and late interest (CMN Res. 4,882).
- Can't pay? Renegotiate an installment that fits your budget before accepting any deal.
This guide follows Brazilian rules for loans, financing and store installment plans.
Which case is yours?
Overdue installments: 10 steps to catch up
1List every overdue installment
- For each contract, note the creditor, installment number, original amount, due date and days late.
- Mark contracts with a pledged asset: home or vehicle financing.
- Find forgotten bank debts in the Central Bank's Registrato, free, with a gov.br silver or gold account.
- Work out what's left each month after housing, food and basic bills. That's your limit for catching up.
2Understand what being late costs
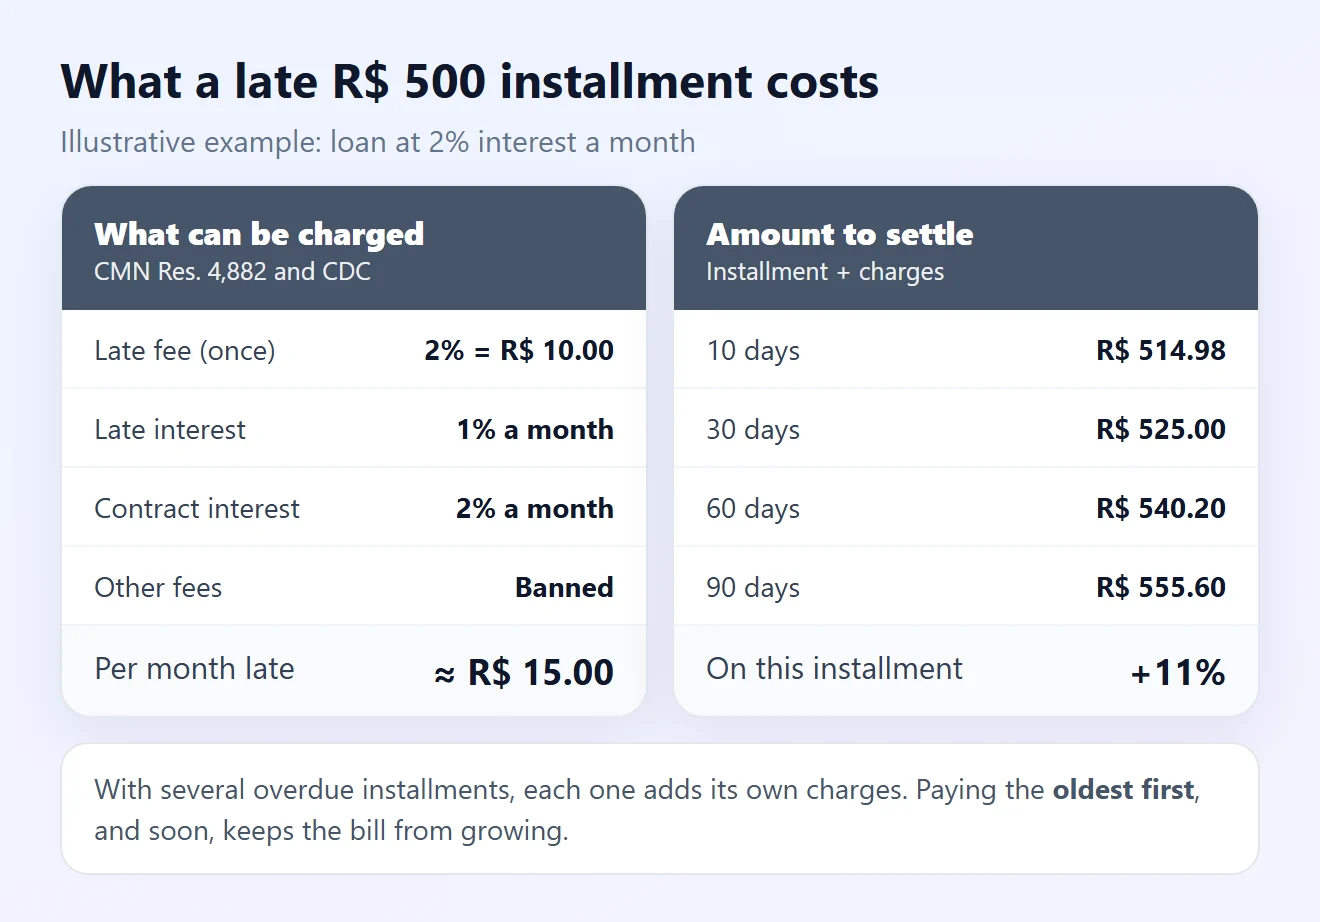
For loans, financing and credit card bills, CMN Resolution 4,882 says banks may charge for late payment only:
- contract interest per day late, at the contract rate (on credit cards, the revolving rate);
- a late fee, as set by law: for consumer purchases and credit, up to 2% of the installment (CDC, art. 52, § 1);
- late interest, as set by law and the contract.
Any other late-payment charge is banned, and the method must be in the contract. Be wary of a “collection fee” or “commission” added to the boleto.
3Choose which installment to pay first
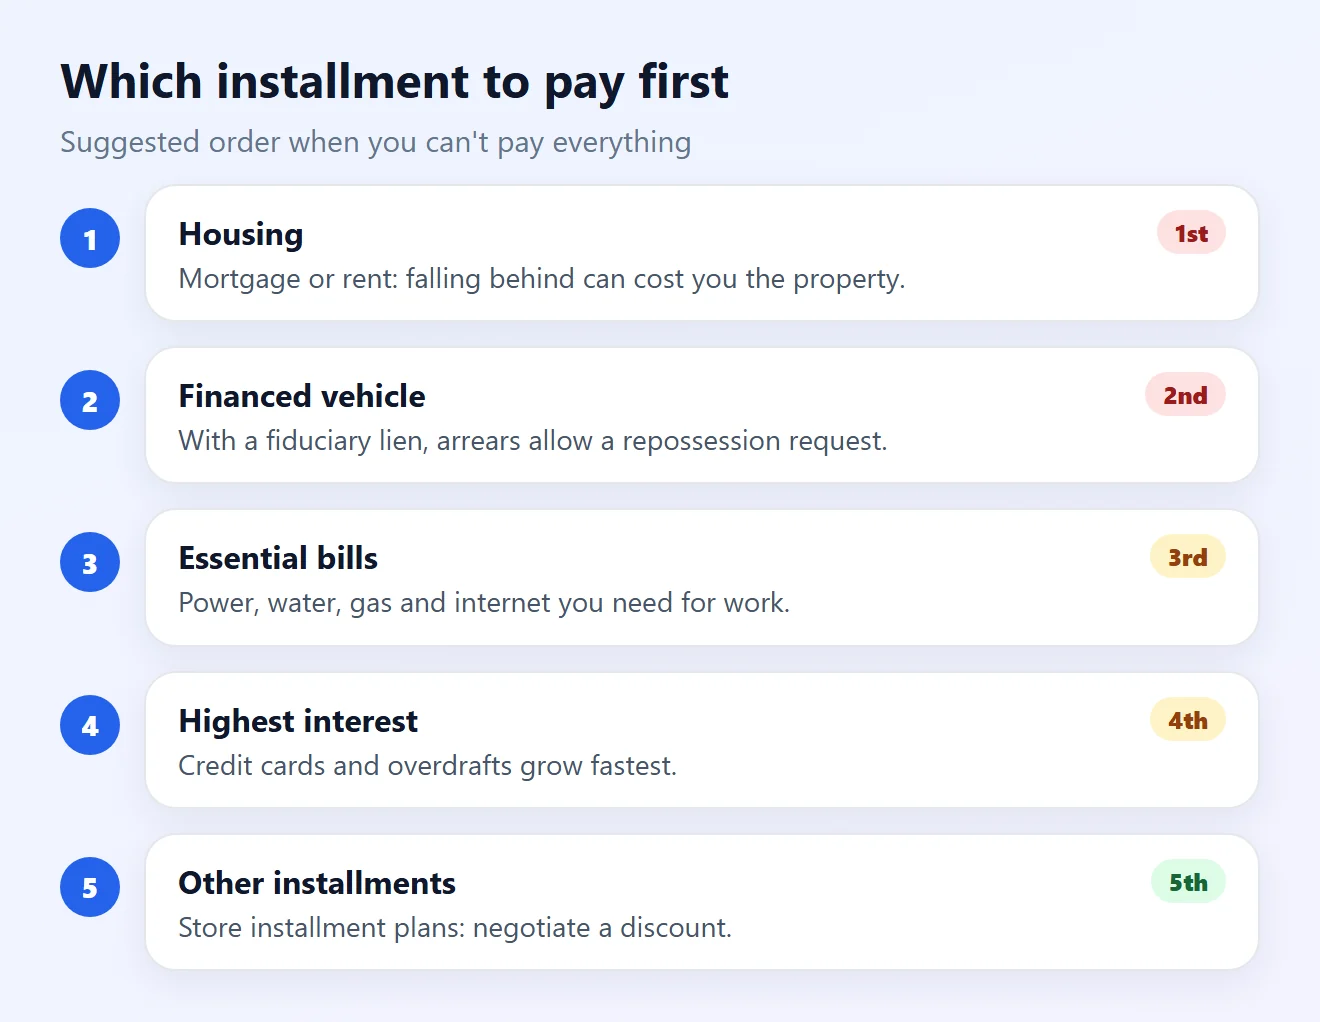
- First, whatever could cost you an essential asset: financed home and car (steps 6 and 7).
- Then power, water and gas, which can be cut off.
- Next, the highest-interest debts, such as credit cards and the overdraft.
- Within the same contract, pay the oldest installment first: it builds up the most charges.
4Contact the creditor before it piles up
- Reach the creditor through its app, website, customer service or branch. Don't use links received by message.
- Explain why you're late (lost income, illness) and say how much you can pay each month.
- Ask for the updated amount of each installment, showing the late fee, late interest and contract interest, and note the protocol number.
The sooner you negotiate, the smaller the bill and the better your chances of keeping the original contract.
5Choose the best way to catch up
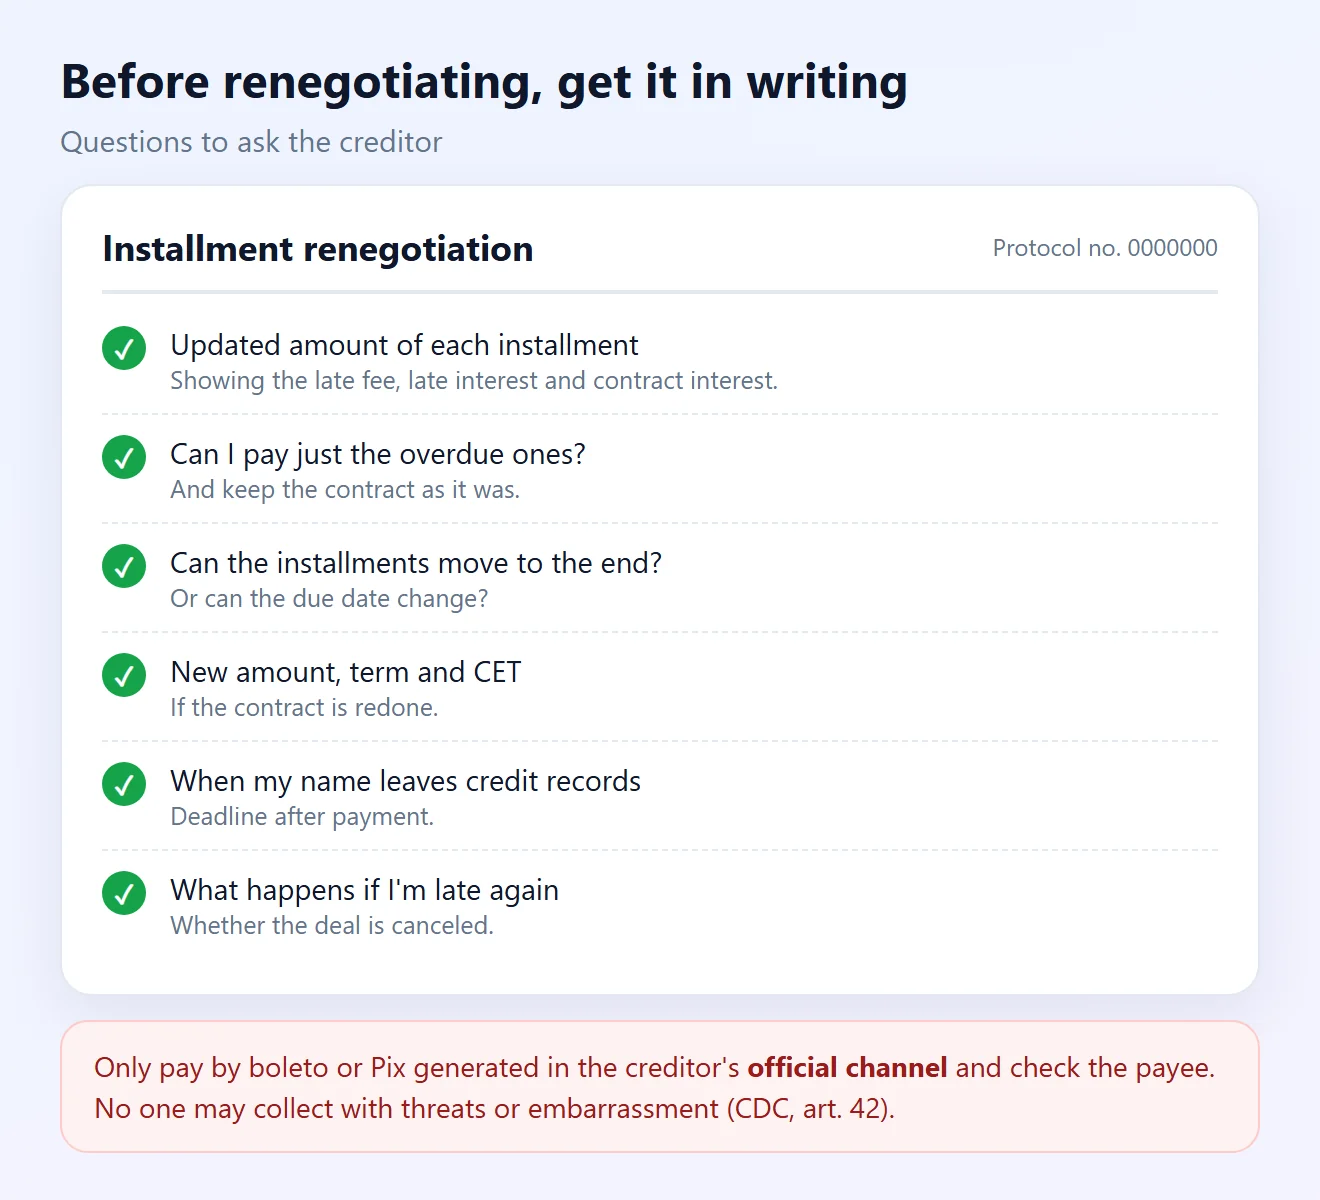
Ask the creditor which options it offers. The most common are:
- Pay only the overdue ones with charges and keep the contract as it was.
- Move the overdue installments to the end of the contract or change the due date.
- Renegotiate the balance into a new contract. Compare the new CET (total effective cost) and the total paid before accepting.
Get everything in writing. Step by step in how to negotiate debt with a bank.
6Financed car: act before repossession
Most vehicle financing in Brazil uses a fiduciary lien (alienação fiduciária): the car stays in the bank's name until it's paid off. Under Decree-Law 911/1969:
- Default starts the moment the installment is past due and can be proven by registered letter with return receipt.
- Once default is proven, the creditor can ask a court for repossession (busca e apreensão), granted by injunction.
- After the injunction is carried out, you have 5 days to pay the entire outstanding debt and get the car back. After that, ownership passes to the creditor.
Got the letter? Contact the bank right away to pay or renegotiate the overdue installments. The Public Defender's Office gives free guidance.
7Financed home: don't ignore the registry notice
In home financing with a fiduciary lien (Law 9,514/1997, art. 26):
- When an installment is overdue, the creditor asks the property registry office to serve you notice.
- From that notice, you have 15 days to pay the overdue installments and those falling due until payment, plus interest, fees, charges and costs.
- If you don't pay, ownership of the property is consolidated in the creditor's name, which can later auction it.
Before it gets that far, ask the bank to add the installments to the balance or for another renegotiation.
8Know your rights when being collected
- Under the CDC (art. 42), you can't be ridiculed, embarrassed or threatened during collection.
- Every collection document must show the creditor's name, address and CPF or CNPJ (CDC, art. 42-A).
- Charged and paid an undue amount? You're entitled to double what you overpaid back, with inflation adjustment and interest, unless it was a justifiable mistake.
Complain to customer service, the Ombudsman and consumidor.gov.br or Procon.
9Protect your credit record
- Before being added to a default list, you must receive written notice (CDC, art. 43, § 2).
- After full payment, the creditor has 5 business days to request your name's removal (STJ Precedent 548).
Already listed? See negative credit record in Brazil: check it free and clear it.
10Avoid falling behind again
- Ask to move the due date to just after payday.
- Use automatic debit only if you're sure of the balance, so you don't slip into the overdraft.
- Build a small reserve, even if it's just one installment.
- If your installments don't fit your income even after cutting costs, learn about Brazil's over-indebtedness law.
Situation and what to do
| Situation | Risk | What to do |
|---|---|---|
| One installment a few days late | Low | Pay it with charges as soon as possible (step 2) |
| Several installments on different contracts | Medium | Prioritize and contact each creditor (steps 3 and 4) |
| Installment no longer fits the budget | Medium | Renegotiate term or amount (step 5) |
| Letter from the bank about the car | High | Pay or renegotiate now (step 6) |
| Registry notice about the home | Very high | Pay within 15 days or negotiate (step 7) |
| Income can't cover the installments | Very high | Over-indebtedness: Procon or Public Defender (step 10) |
Frequently asked questions
What charges can a bank add to an overdue installment?
Under CMN Resolution 4,882, only contract interest per day late (at the contract rate), a late fee and late interest as set by law. Any other late-payment charge is banned.
What's the maximum late fee on an installment?
For consumer purchases and credit in Brazil, the late fee can't exceed 2% of the installment (CDC, art. 52, § 1). It's charged once, not every month.
How many missed installments before the bank can take the car?
The law doesn't set a number. Under Decree-Law 911/1969, default exists from the due date and, once proven by registered letter, the creditor can ask a court for repossession.
My car was repossessed. Can I get it back?
Under Decree-Law 911/1969, within 5 days after the injunction is carried out you can pay the entire outstanding debt, at the amounts presented by the creditor, and get the vehicle back.
How long do I have to pay an overdue home installment?
After notice from the property registry office, you have 15 days to pay the overdue installments and charges (Law 9,514/1997, art. 26). Without payment, ownership passes to the creditor.
Should I pay the oldest or the newest installment?
Within the same contract, the oldest: it builds up the most interest and fees. Across contracts, prioritize those with a pledged asset and essential bills.
Can the creditor call me and make threats?
No. Under the CDC (art. 42), collection can't ridicule you or use embarrassment or threats. File a complaint with Procon or consumidor.gov.br.
Does one late installment hurt my credit record?
An overdue debt can be sent to a default list, but you must be notified in writing first (CDC, art. 43, § 2). Paying soon avoids the record.
Can I ask to move overdue installments to the end of the contract?
You can ask. There's no legal obligation to accept, but many creditors offer it. Get the terms in writing and compare the total paid.
What if my installments no longer fit my income?
Renegotiate the term and amount with each creditor. If the total still doesn't fit, go to Procon or the Public Defender's Office and ask for an over-indebtedness repayment plan.
Related content
More practical solutions in Debt.

Compound Interest on Debt: How to Understand and Prevent Balance Growth
Entenda how to the compound interest aumentam the amount of a debt to the longo of the time, how to identify the encargos cobrados and quais atitudes helpm the reducesir the impact financial.
 15 minutes

How to Get Out of Debt: A Complete Guide to Reorganizing Your Finances
Learn how to sair of the debts with estratégias práticas of organization financial, negotiation of débitos, control of expenses and planning for recuperar your estabilidade financial.
30 minutes

Negative Credit Record in Brazil: How to Check and Resolve Outstanding Debts
Learn how to check for a negative credit record in Brazil, identify outstanding debts, negotiate with creditors, and track the regularization of your CPF safely.
15 minutes
Sources
- Central Bank of Brazil: CMN Resolution 4,882/2020 on late-payment charges (in Portuguese)
- Planalto: Consumer Protection Code, Law 8,078/1990, arts. 42, 43 and 52 (in Portuguese)
- Planalto: Decree-Law 911/1969 on fiduciary liens over movable property (in Portuguese)
- Planalto: Law 9,514/1997 on fiduciary liens over real estate, art. 26 (in Portuguese)
- STJ: five business days to request removal from a default list, Precedent 548 (in Portuguese)
- Central Bank of Brazil: Registrato (in Portuguese)
- Consumidor.gov.br: complaints against companies and banks (in Portuguese)
The screens and simulation in this guide are illustrations made by Fixfy. The simulation uses 2% monthly contract interest, 1% monthly late interest and a 2% late fee; your contract's rates may differ. This content is for information only and isn't legal advice.